Personal Finance Tips 2026: Build Wealth on Any Salary
The best personal finance tips do not require a six-figure salary, a finance degree, or complicated spreadsheets. They rely on a handful of habits repeated consistently over time. In 2026, with prices still climbing and digital tools everywhere, the people who quietly build wealth are the ones who master the basics and stick with them. This guide gives you a clear, practical roadmap you can start using this week, whatever your income.
Money stress is rarely about how much you earn. It is about how much you keep, how you spend, and whether your money has a plan. Let us fix that with steps anyone can follow.
Personal Finance Tips That Start With a Budget
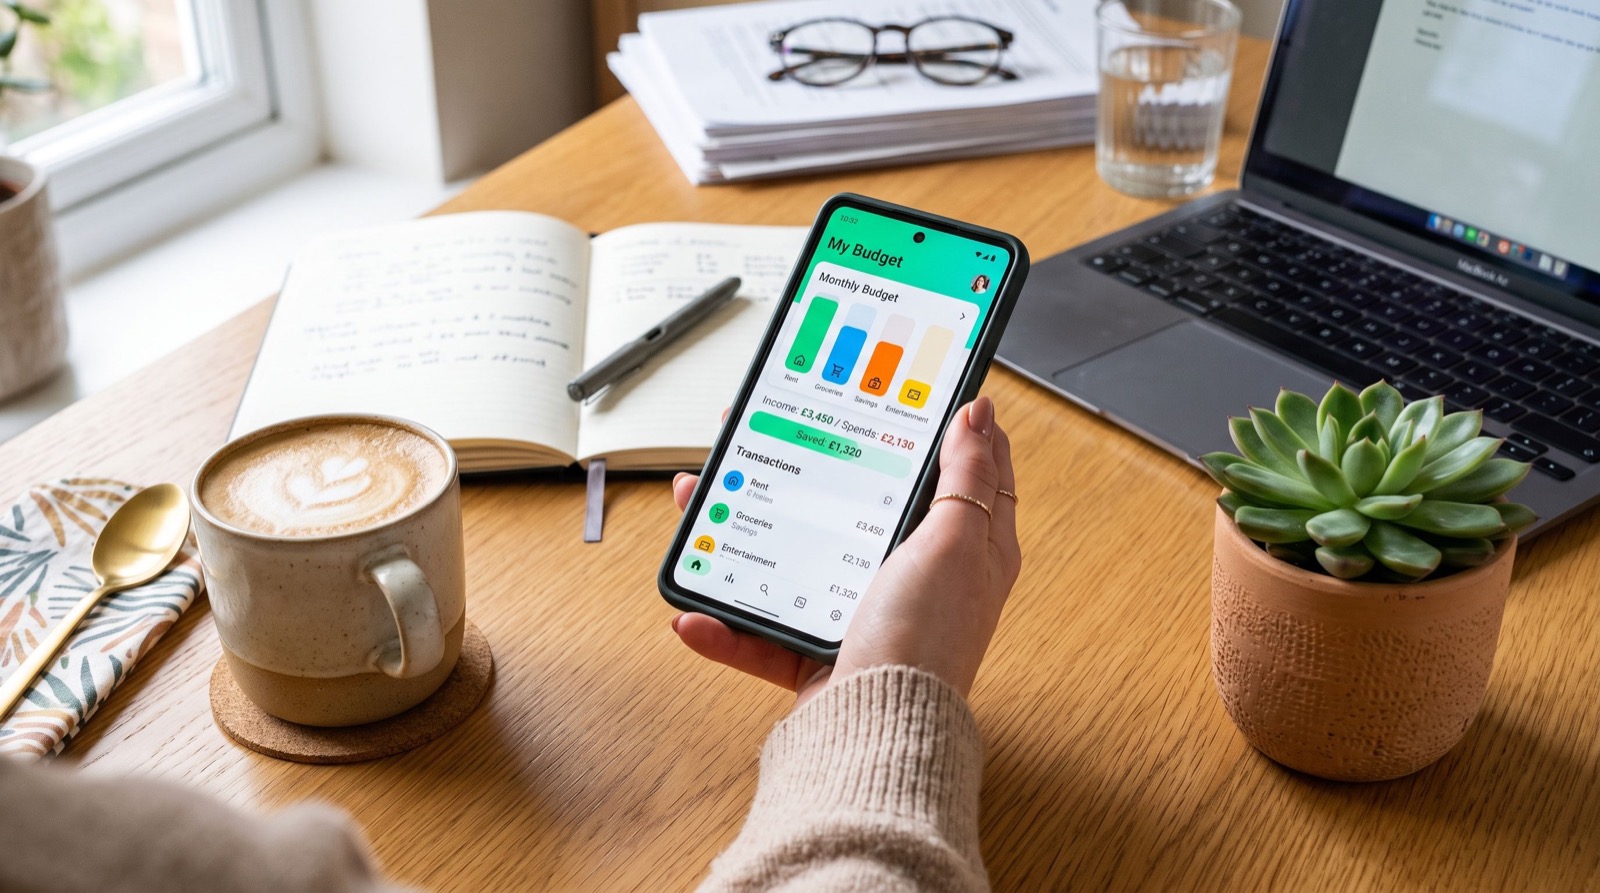
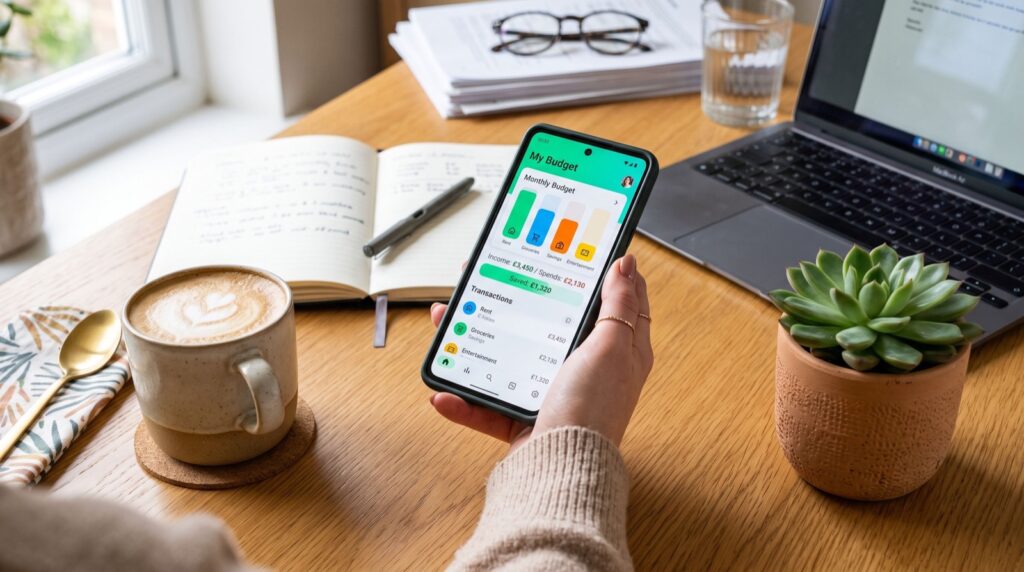
Every strong financial plan begins with knowing where your money goes. A budget is not a punishment; it is a plan that gives every dollar a job. Track your spending for one month, then group it into needs, wants, and savings. Most people are shocked by how much leaks out on subscriptions and impulse buys.
A popular framework is the 50/30/20 rule: half your income to needs, thirty percent to wants, and twenty percent to savings and debt. Treat it as a starting point, not a law. If your rent eats more than half your income, adjust the ratios and cut elsewhere.
How much should you save each month?
Aim to save at least twenty percent of take-home pay, but start with whatever you can, even five percent. The habit matters more than the amount at first. The Federal Reserve has reported that a large share of adults would struggle to cover an unexpected several-hundred-dollar expense, which is exactly why an emergency fund comes first.
- Emergency fund: build three to six months of expenses over time.
- Automate it: transfer savings on payday before you can spend.
- Start small: a modest recurring amount beats waiting for “extra” money.
- Separate accounts: keep savings away from daily spending.
Tackle Debt Before It Tackles You
High-interest debt is the single biggest obstacle to building wealth. Credit-card balances can grow faster than most investments, so clearing them is effectively a guaranteed return. Two proven methods work well, and the right one depends on your personality.
| Method | How It Works | Best For |
|---|---|---|
| Debt Snowball | Pay smallest balance first | Motivation from quick wins |
| Debt Avalanche | Pay highest interest first | Saving the most money |
| Balance Transfer | Move debt to a 0% card | Disciplined payoff plans |
Whichever you choose, stop adding new debt while you pay down the old. Pairing a payoff plan with practical personal finance tips keeps you focused when motivation dips, which it inevitably will.
Should you save or pay off debt first?
Do both in the right order. Build a small starter emergency fund first, roughly one month of expenses, so a surprise bill does not push you back onto credit cards. Then throw everything at high-interest debt. Once that is gone, grow your full emergency fund and start investing in earnest.
Make Your Money Grow
Saving protects you; investing builds you. Once your high-interest debt is cleared and your emergency fund is solid, put money to work in low-cost, diversified investments. Time in the market matters more than timing the market, so starting early beats starting big.
Modern money apps make investing accessible with fractional shares and automatic contributions. If you handle transfers and everyday spending digitally, learning the strongest best money apps for saving and investing helps you automate the whole process and stay consistent.
- Contribute enough to capture any employer retirement match first.
- Open a low-cost index fund or retirement account.
- Automate monthly contributions so investing becomes a habit.
- Increase contributions slightly each time you get a raise.
Protect What You Build
Wealth is fragile without protection. Review your insurance, guard your accounts with strong passwords and two-factor authentication, and stay alert to fraud. A single scam or uninsured emergency can undo years of progress in days.
Here is a concrete tip that pays off: schedule a 30-minute “money date” with yourself every month. Review spending, check savings, and adjust one thing. That small ritual keeps you engaged and catches problems early. When decisions get complex, consulting dependable specialists beats guessing on high-stakes choices like taxes or estate planning.
Boost Your Income and Avoid Lifestyle Creep
Cutting costs has a floor, but growing income has no ceiling. In 2026, side income has never been more accessible, from freelancing and tutoring to selling skills online. Even a modest extra stream, directed entirely toward debt or savings, can shorten your timeline to financial security by years.
The catch is lifestyle creep, the quiet tendency to spend more every time you earn more. A raise feels great, but if your expenses rise to match, your savings rate never improves. The fix is simple discipline: whenever your income grows, bank at least half of the increase before you adjust your spending.
Negotiating also pays off more than most people realize. Asking for a raise, shopping insurance quotes annually, and calling providers to lower recurring bills can free up meaningful money with a single conversation. These wins are one-time efforts that keep paying you month after month.
Finally, protect your growing income with the right documents and knowledge. Understand your tax withholdings, contribute to tax-advantaged retirement accounts, and keep learning. Financial literacy compounds much like money does, so every hour you invest in understanding your finances pays dividends for decades.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start by tracking your spending, building a small emergency fund, and eliminating high-interest debt. Automate your savings so it happens without willpower. Master these basics before worrying about advanced investing strategies.
How do I start saving with a low income?
Begin with a tiny automatic transfer, even a few dollars per payday, and increase it gradually. Cut one recurring expense you rarely use and redirect that money to savings. Consistency, not size, builds the habit that leads to real progress.
Is it better to invest or pay off debt?
Clear high-interest debt first, since its cost usually outpaces investment returns. Keep a small emergency fund so surprises do not push you back into debt. Once high-interest balances are gone, prioritize investing for long-term growth.
How much emergency savings do I really need?
Aim for three to six months of essential expenses. If your income is irregular or you support a family, lean toward the higher end. Build it gradually so the goal feels achievable rather than overwhelming.
Final Thoughts
These personal finance tips prove that building wealth in 2026 is less about earning more and more about managing what you have. Budget with intention, crush high-interest debt, automate your savings, and invest for the long haul. Protect your progress and review it monthly. Do the basics consistently, and time will do the heavy lifting. Ready to take charge? Pick one tip above and put it into action before the week ends.